This document must not be disclosed, published, or distributed, in whole or in part, directly or indirectly, in any country where such disclosure, publication, or distribution would constitute a violation of applicable laws or regulations in that jurisdiction.
October 10, 2026
Voluntary tender offer on all the ordinary shares in Trevi-Finanziaria Industriale launched by Webuild
Milan, 10 October 2026 - With reference to the voluntary tender offer launched by Webuild S.p.A. (“Webuild”) on all the ordinary shares in Trevi-Finanziaria Industriale S.p.A. (“Trevi”), announced to the market on July 29, 2026 pursuant to Articles 102 of Legislative Decree No. 58 of February 24, 1998 (the “TUF”) and 37 of the Regulation adopted by CONSOB Resolution No. 11971 of May 14, 1999 (the “Offer”), at the request of CONSOB pursuant to Articles 103, paragraph 2, and 114, paragraph 5, of the TUF, Webuild hereby announces the following, supplementing and amending its previous communications, including those of a promotional nature.
- Comparison of the consideration values of the offers for Trevi shares launched by Webuild and ICOP S.p.A. Società Benefit (“ICOP”), respectively
It is noted that, for purposes of comparing the consideration values of the offers for Trevi shares launched by Webuild and ICOP, respectively, it is necessary to take into account the implied monetary value of the consideration offered in shares by ICOP, calculated on the basis of the market prices recorded on the various relevant dates.
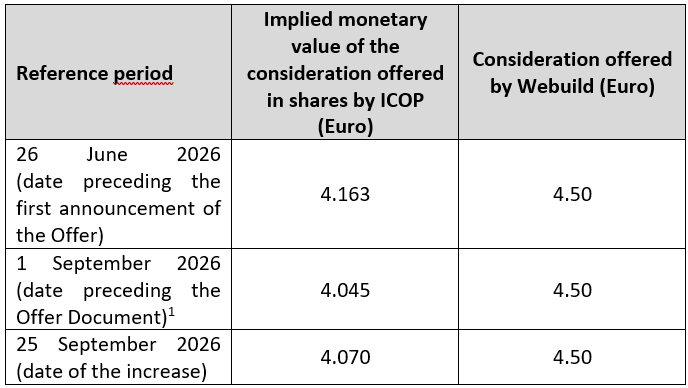
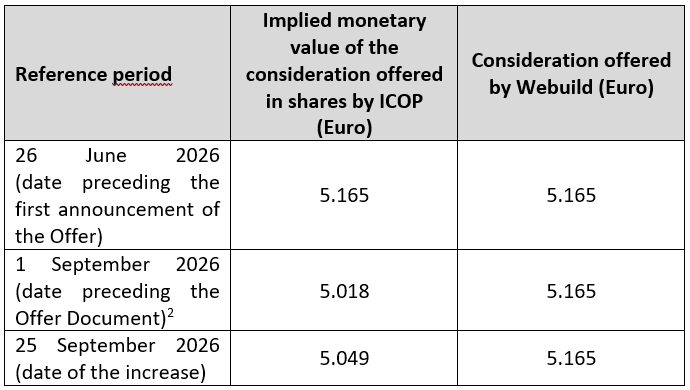
The economic value of the offer launched by ICOP for each Trevi share, calculated on the basis of its implied monetary value on the relevant dates, is set out below, compared with the cash consideration of the offer launched by Webuild.
Implied monetary value of the consideration offered in shares by ICOP based on an exchange ratio of 0.133 ICOP shares for each Trevi share (prior to the increase in consideration), compared with the cash consideration offered by Webuild
Implied monetary value of the consideration offered in shares by ICOP based on an exchange ratio of 0.165 ICOP shares for each Trevi share, compared with the cash consideration offered by Webuild (following the increase in consideration)
The economic value of the offer launched by ICOP for each Trevi share, calculated on the basis of its implied monetary value as at October 9, 2026 (based on an exchange ratio of 0.165 ICOP shares for each Trevi share), is set out below, compared with the cash consideration of the offer launched by Webuild (following the increase in consideration).
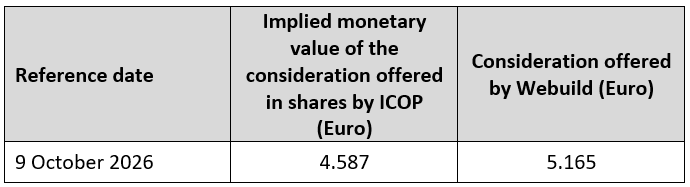
As indicated by ICOP in its Offer Document, the implied monetary value of the consideration offered in shares by ICOP varies depending on the stock market price of ICOP shares, including during the acceptance period and up to the payment date. The consideration of Webuild’s offer, equal to Euro 5.165 per Trevi share, is entirely in cash and is not subject to changes based on stock market performance.
- Clarifications regarding the economic value of ICOP’s offer
With reference to the economic value of ICOP’s offer estimated by Webuild at Euro 3.40, as indicated in previous communications, and consistently with what was already noted therein, it is clarified that:
- such economic value is the result of discretionary analyses carried out by Webuild itself, the offeror of an offer competing with ICOP’s, and must therefore be regarded as supplementary information to the values calculated using the method and on the dates indicated in the preceding section;
- the same economic value was determined using the valuations made by the financial advisors of Trevi’s Board of Directors (i.e., Mediobanca and Vitale), whose sole purpose was to assist Trevi’s Board of Directors in issuing its fairness opinion on the offers launched by Webuild and ICOP;
- the valuations of the advisors Mediobanca and Vitale identify, for the Trevi shares subject to the Offer, ranges of values for the offer launched by Webuild and ranges of exchange ratios for the offer launched by ICOP, using different valuation methodologies, without indicating a specific value for Trevi shares. The value of Euro 3.40 calculated by Webuild is instead a specific value derived from an average implied value of ICOP shares (approximately Euro 21) obtained from average data (both of the ranges of Trevi share values and of the ranges of exchange ratios determined by the aforementioned advisors), moreover in the absence of known indications as to the degree of weighting and the resulting significance of such data;
- accordingly, Webuild’s estimate must be understood as an entirely discretionary analysis in the selection of the Trevi-sourced elements used for its calculation.
Webuild adopted this approach as it believes that it may provide useful information, since it is based on the analyses carried out by the advisors of Trevi’s Board of Directors for the purposes of the fairness assessment of the consideration of both offers, which use fundamental (DCF) and market (market multiples) valuation methodologies that are independent of the stock market prices of Trevi and ICOP shares.
The methodology used to determine the average value of Euro 3.4 per share is set out below.
This analysis was carried out by Webuild in order to reconstruct the implied value, for each Trevi share, of the consideration offered in shares by ICOP on the basis of the exchange ratio relating to ICOP’s offer and the valuations relating to ICOP and Trevi that can be inferred from the analyses conducted by the advisors of Trevi’s Board of Directors (i.e., the exchange ratio relating to ICOP’s offer and the value attributed to Trevi shares in the analyses relating to Webuild’s offer).
In particular:
- in Trevi’s communication regarding Webuild’s offer, a value range for Trevi shares is indicated between Euro 5.1 and Euro 6.1 under the DCF method and between Euro 4.9 and Euro 5.7 under the market multiples method;
- in Trevi’s communication regarding ICOP’s offer, an exchange ratio between 0.251 and 0.312 ICOP shares for each Trevi share is indicated under the DCF method and between 0.222 and 0.301 ICOP shares for each Trevi share under the market multiples method.
Based on the above valuations, by combining, for each method, the minimum and maximum value attributed to Trevi shares with the maximum and minimum exchange ratio, respectively, the implied value of ICOP shares was estimated (as the ratio between the value of Trevi and the exchange ratio): (i) between approximately Euro 16.3 and approximately Euro 24.3 under the DCF method; and (ii) between approximately Euro 16.3 and approximately Euro 25.7 under the market multiples method.
Therefore, based on such implied values of ICOP and the exchange ratio of 0.165x, a value per Trevi share between approximately Euro 2.7 and Euro 4.0 is obtained under the DCF method and between approximately Euro 2.7 and Euro 4.2 under the market multiples method. The average of the above implied per-share values is approximately Euro 3.4 per share.
- Liquidity of ICOP shares
With regard to the ratio of trading volumes to share capital over the last twelve months (the so-called turnover), which over the last twelve months was equal to approximately 11% of ICOP’s share capital, compared with approximately 184% of Trevi’s, it is clarified that such ratio, calculated on the free float, is equal to approximately 70% for ICOP and approximately 234% for Trevi.
It is noted that ICOP’s recent uplisting and the dilution of its significant shareholder if the relevant offer is successful, resulting in an increase in market capitalisation, may affect the liquidity of ICOP shares in the future.
- ICOP’s indebtedness
With reference to the information concerning ICOP’s indebtedness, we report that ICOP’s Offer Document indicates that the increase in its net indebtedness compared with December 31, 2024 mainly reflects the change in the company’s perimeter resulting from acquisitions made and investments undertaken.
- ICOP’s 2025 EV/EBIT multiple
With reference to ICOP’s 2025 EV/EBIT multiple (i.e., 21.7x), it is clarified that this is a reported figure, taken from ICOP’s Offer Document and presented therein for informational purposes to compare it with average sector data, whereas the EV/EBIT multiple used by ICOP to “value itself”, within the valuation methodologies selected to determine the consideration, is the multiple resulting from the analysis of the three comparable companies selected by ICOP (i.e., Trevi, Sterling Infrastructure and Keller Group), constructed on the basis of expected 2026-2027 EBIT data.
***
Finally, please note that for any requests or information regarding the Offer, Trevi shareholders may use the following information channels, which will be available throughout the Acceptance Period on business days from 9:00AM to 6:00PM (Italian time): (i) the dedicated E-Mail account opatrevi_webuild@georgeson.com; (ii) the toll-free number 800 189039 (for callers from Italy); (iii) the direct line +39 06 45212909 (also for callers from abroad). The Global Information Agent website is www.georgeson.com/it.
This press release and all documents relating to the Offer will be made available, amongst others, on the following websites
***
This communication does not constitute, and is not intended to constitute, an offer, invitation or solicitation to buy or otherwise acquire, subscribe for, sell or otherwise dispose of any financial instruments, and no sale, issuance or transfer of financial instruments of Trevi Finanziaria Industriale S.p.A. will be made in any country in violation of the applicable laws. The Offer will be made by means of publication of the relevant Offer Document, subject to CONSOB approval. The Offer Document will contain the full description of the terms and conditions of the Offer, including acceptance procedures. The publication or dissemination of this communication in countries other than Italy may be subject to restrictions under applicable law, and accordingly any person subject to the laws of any country other than Italy is required to independently inform itself of any restrictions under applicable laws and to ensure compliance therewith. Any failure to comply with such restrictions may constitute a violation of the applicable laws of the relevant country. To the fullest extent permitted by applicable law, the parties involved in the Offer shall be deemed exempt from any liability or adverse consequence arising from the violation of such restrictions by such persons. This communication has been prepared in accordance with Italian law and the information disclosed herein may differ from that which would have been disclosed had the communication been prepared in accordance with the laws of countries other than Italy. No copy of this communication or any other documents relating to the Offer will be, or may be, mailed or otherwise transmitted or distributed in or from any country where the provisions of local law may give rise to civil, criminal or regulatory risks if information concerning the Offer is transmitted or made available to shareholders of Trevi Finanziaria Industriale S.p.A. in such country or other countries where such actions would constitute a violation of the relevant laws, and any person receiving such documents (including custodians, nominees or trustees) must not mail or otherwise transmit or distribute them to or from any such country. The contents of this communication are of an informational and preliminary nature and should not be construed as investment advice. The statements contained herein have not been independently verified. No representation or warranty, express or implied, is made as to, and no reliance should be placed on, the fairness, accuracy, completeness, correctness or reliability of the information contained herein. Neither Webuild S.p.A. nor any of its representatives nor its direct or indirect controlling shareholders shall accept any liability (whether in negligence or otherwise) arising in any way in connection with such information or in connection with any loss arising from its use or otherwise arising in connection with this communication. By accessing this communication, you agree to be bound by the foregoing limitations.
Calculated based on the official price of ICOP shares for the last open trading day preceding the date of ICOP’s Offer Document (Euro 30.415), as reported in that document.
Calculated based on the official price of ICOP shares for the last open trading day preceding the date of ICOP’s Offer Document (Euro 30.415), as reported in that document.
Calculated based on the closing price of ICOP shares as at October 9, 2026, equal to Euro 27.80.
Calculation based on Bloomberg trading volumes, the number of ICOP shares indicated in ICOP’s Offer Document (page 48), the number of Trevi shares indicated in Trevi’s Board of Directors’ communication regarding ICOP’s offer dated September 10, 2026 (page 10), the free float indicated in ICOP’s information prospectus relating to the uplisting, and Trevi’s free float available on Bloomberg.
Percentages calculated based on an assumed free float of 16.2% for ICOP and an assumed free float of 78.7% for Trevi.